
USDA Home Loan Rates Today: The Quick Answer
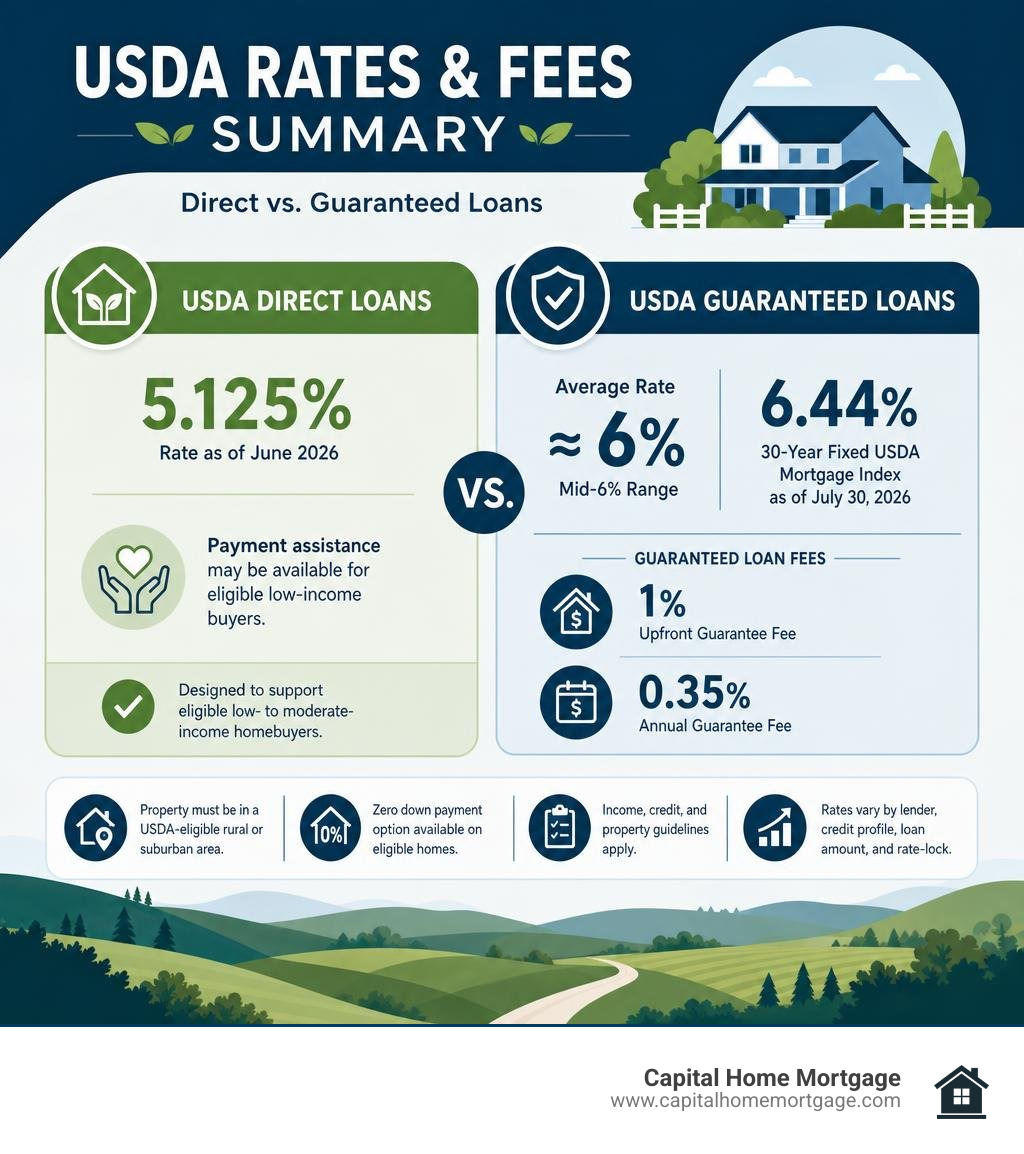
As of the latest 2026 benchmarks, USDA Guaranteed loan rates average around the mid-6% range, with a 30-year fixed USDA mortgage index at 6.44% on July 30, 2026. Your actual rate can vary by lender, credit profile, loan amount, and rate-lock date. USDA Section 502 Direct loans are different: the published rate was 5.125% as of June 2026, with possible payment assistance for eligible low-income buyers.
For a fast answer on usda home loan rates today:
- Check a personalized quote from a USDA-approved lender, not only a national average.
- Confirm that the home is in a USDA-eligible rural or suburban area.
- Compare the full cost, including the 1% upfront guarantee fee and 0.35% annual fee on Guaranteed loans.
USDA financing can be a strong fit for qualified buyers because it offers zero down payment and can finance 100% of an eligible home’s purchase price. The tradeoff is that income, location, property type, and credit rules all matter.
I’m Dale Gremillion, a manager at Capital Home Mortgage with more than 26 years of mortgage-industry management experience. I help buyers understand usda home loan rates today alongside FHA, VA, conventional, purchase, and refinance options so they can make a clearer financing decision.
Understanding USDA Home Loan Rates Today

When researching mortgage options, many buyers assume zero-down programs are strictly reserved for active military personnel or farming operations. In reality, the U.S. Department of Agriculture (USDA) backs home loan programs designed to foster homeownership across eligible rural and growing suburban areas.
To understand where borrowing costs stand in September 2026, it helps to track daily market movements. According to the 30 Year Fixed Rate USDA Mortgage Index, benchmark indices have hovered in the mid-6% range, following broader macroeconomic indicators and Federal Reserve policy shifts. While this index sits above its historical long-term average of 4.99%, USDA financing continues to provide competitive pricing compared to standard retail mortgages.
We manage the entire lifecycle of USDA Home Loans through in-house processing and underwriting. This structure eliminates third-party delays and gives borrowers clear, direct guidance on how current interest rates translate into real monthly payments.
How USDA Home Loan Rates Today Compare to Conventional, FHA, and VA Options
Evaluating loan options requires looking at both the note rate and ongoing mortgage insurance costs. Standard conventional mortgages require private mortgage insurance (PMI) if you put down less than 20%, whereas Federal Housing Administration (FHA) loans require both an upfront Mortgage Insurance Premium (MIP) of 1.75% and an annual fee of around 0.55%.
By comparison, USDA Guaranteed loans feature an upfront guarantee fee of 1.00% and an annual fee of just 0.35%. This lower ongoing fee structure often produces a lower monthly payment than an FHA loan with an identical interest rate.
| Feature / Program | USDA Guaranteed Loan | FHA Loan | VA Loan | Conventional Loan |
|---|---|---|---|---|
| Minimum Down Payment | 0% | 3.5% | 0% | 3% to 5% |
| Upfront Fee | 1.00% Guarantee Fee | 1.75% Upfront MIP | 1.25% – 3.3% Funding Fee | None |
| Annual/Monthly Fee | 0.35% Annual Fee | ~0.55% Annual MIP | None | Private Mortgage Insurance (PMI) |
| Credit Score Typical Min | 640 (automated) | 580 | 580 – 620 | 620 |
| Geographic Restriction | USDA-eligible areas | Nationwide | Nationwide | Nationwide |
| Income Limits | Max 115% of AMI | None | None | None (standard programs) |
Tracking USDA Home Loan Rates Today: Direct vs. Guaranteed Loans
It is essential to distinguish between the two primary USDA loan programs:
- USDA Section 502 Direct Housing Loans: Managed directly by the federal government, these loans serve very-low to low-income applicants who lack safe, decent housing. As of June 2026, the published interest rate for Direct loans is a flat 5.125%, with subsidies that can reduce payment rates significantly for qualifying households. Review the official guidelines for Single Family Housing Direct Home Loans to see standard qualification parameters.
- USDA Section 502 Guaranteed Loans: Issued by approved private mortgage lenders like us and guaranteed by the USDA. These interest rates fluctuate with daily capital markets and typically range between 6.17% and 7.60% APR depending on credit score, debt-to-income (DTI) ratios, and loan terms.
How to Qualify for a USDA Loan at Current Rates

Qualifying for a USDA-backed mortgage involves meeting both borrower-specific standards and property-specific requirements. Because the government guarantees up to 90% of the loan amount for approved private lenders, underwriting guidelines remain accessible while managing overall portfolio risk.
- Credit Benchmarks: Most automated underwriting systems require a minimum credit score of 640 for streamlined approval. Borrowers with scores below 640 may still qualify through manual underwriting, provided they demonstrate strong compensating factors such as rental payment history or cash reserves.
- Debt-to-Income (DTI) Ratios: The standard USDA DTI benchmark is 29% for housing costs and 41% for total monthly obligations. Higher ratios can be approved when supported by solid credit profiles and automated underwriting findings.
- Income Caps: The total household income cannot exceed 115% of the Area Median Income (AMI) for the county in which the home is located. Importantly, USDA calculates household income across all adult occupants, regardless of whether they are listed on the loan note.
USDA Property Eligibility and Regional Availability
A common misconception is that USDA loans are only usable for remote farmland. In reality, over 97% of the U.S. landmass is classified as USDA-eligible, covering vast suburban pockets, master-planned communities, and small towns outside major urban centers.
Buyers can check specific addresses against the USDA Rural Development online eligibility maps. Our loan officers frequently guide clients through eligible communities across growing regions, such as Texas USDA Home Loans and California USDA Home Loans.
USDA Fee Structure and Out-of-Pocket Costs
While USDA financing provides a true zero-down payment structure, buyers must account for standard transaction expenses and program fees:
- 1.00% Upfront Guarantee Fee: Calculated on the base loan amount and almost universally financed directly into the mortgage balance.
- 0.35% Annual Fee: Calculated on the remaining principal balance annually and divided into 12 monthly escrow installments.
- Standard Closing Costs: Appraisals, title insurance, recording fees, and prepaid escrow items apply just like any mortgage. Borrowers can cover these through seller concessions (up to 6% of the purchase price is permitted), eligible gift funds, or lender credits.
Step-by-Step Guide to Securing Your USDA Home Loan
Navigating the mortgage journey is straightforward when you follow a structured roadmap:
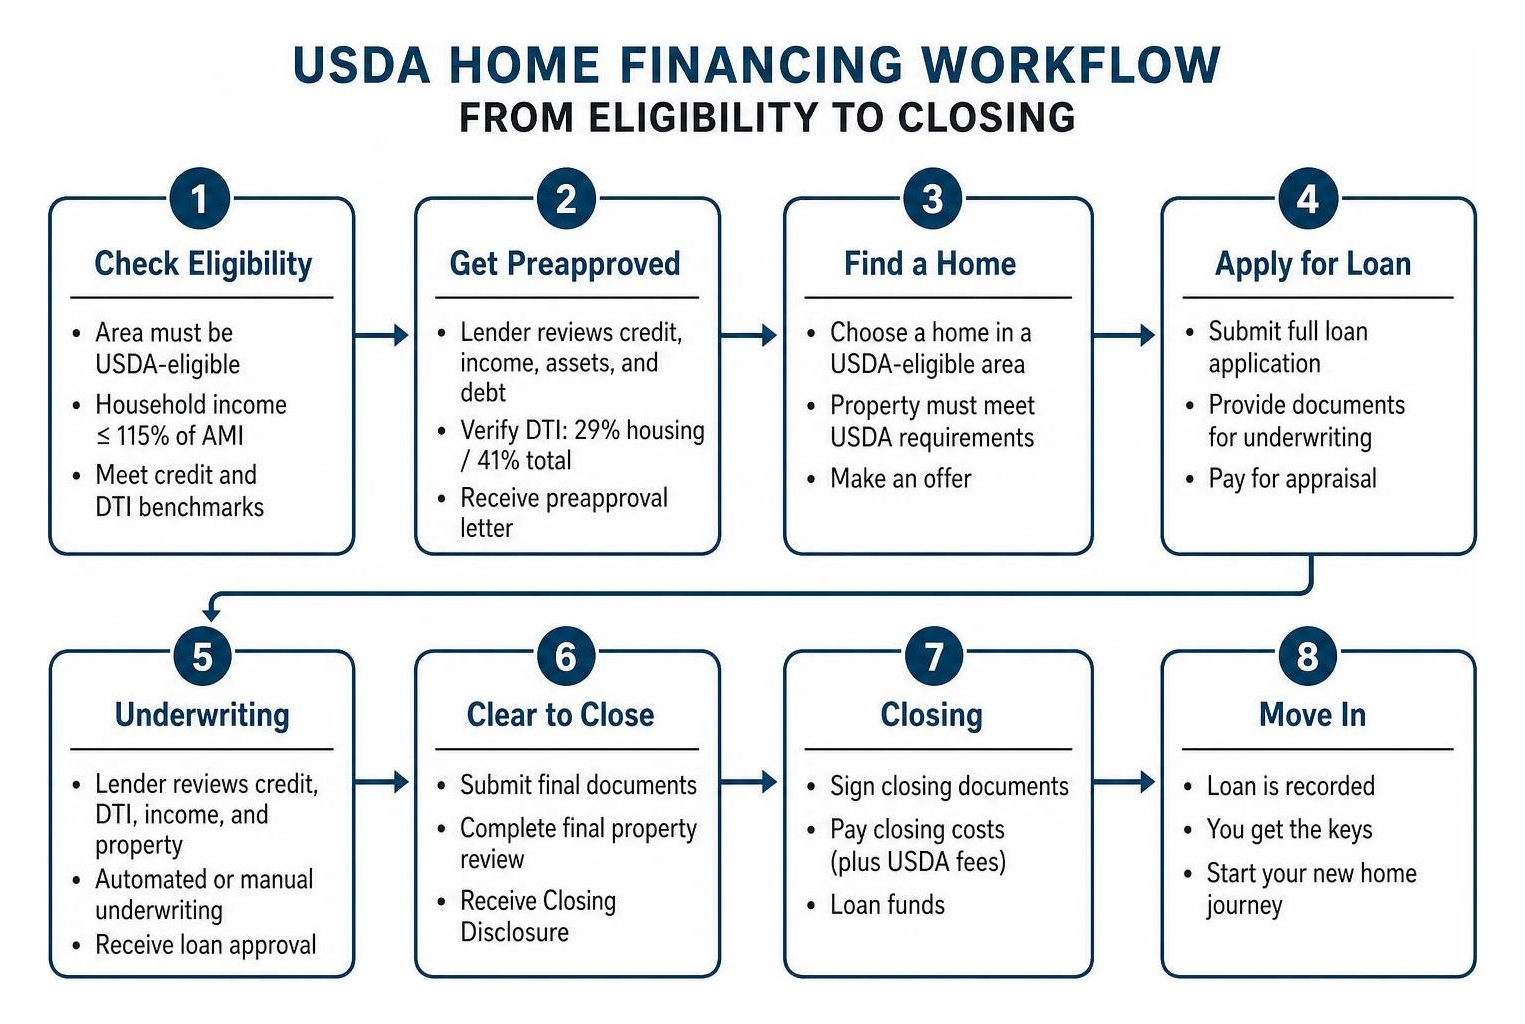
- Check Property and Income Eligibility: Confirm that your gross annual household income falls under your county’s 115% AMI limit and that your target property falls within USDA-designated boundaries.
- Gather Financial Documentation: Assemble recent pay stubs (30 days), W-2 statements (2 years), federal tax returns, and asset statements (2 months).
- Obtain Lender Pre-Approval: Work with our dedicated loan officers to run your application through the automated underwriting system to determine your purchasing power and lock in competitive terms.
- Find an Eligible Home and Make an Offer: Partner with a real estate agent familiar with USDA minimum property standards (ensuring the home is structurally sound, safe, and sanitary).
- Complete Processing, Appraisal, and USDA Review: Our in-house processing and underwriting team reviews the appraisal and completes file verification before submitting the package to the local USDA office for final issuance of the Conditional Commitment.
- Final Approval and Closing: Complete the final closing disclosures, sign loan documents, and receive your keys within a standard 30- to 45-day closing window.
Frequently Asked Questions About USDA Mortgage Rates
What credit score is needed to secure the best USDA mortgage rate?
A credit score of 640 or higher provides access to automated underwriting approval, giving you streamlined processing and the most competitive market interest rates. Applicants with credit scores between 580 and 639 can qualify via manual underwriting by demonstrating stable employment, reliable payment histories, and low overall debt.
How long does USDA loan approval take in 2026?
For USDA Guaranteed loans, closing typically takes between 30 and 45 calendar days. Because our in-house underwriting team handles the processing directly before transmitting the final file to the USDA regional office, delays are minimized. USDA Direct loans administered entirely through government offices often require 60 to 90 days or more.
Can USDA loan guarantee fees be rolled into the mortgage balance?
Yes. The 1.00% upfront guarantee fee can be financed into your total loan balance on top of the home’s purchase price. For example, on a $300,000 home purchase with zero down, the 1% fee ($3,000) can be added directly to the principal balance, bringing your total financed amount to $303,000 and eliminating that out-of-pocket expense at closing.
Conclusion
Securing an affordable home purchase requires balancing interest rates, upfront down payments, and ongoing monthly fees. With zero down payment requirements, low monthly guarantee fees, and broad regional coverage, USDA home financing remains one of the most accessible mortgage programs for homebuyers today.
At Capital Home Mortgage, we provide in-house processing and underwriting alongside dedicated loan-officer support to ensure on-time closings. Whether you are exploring options for Texas USDA Home Loans or looking for zero-down home financing in your local market, connect with our lending team to evaluate current rates and find the right loan for your needs.


