
Find the Right Boca Raton Mortgage Broker for Your Home Loan
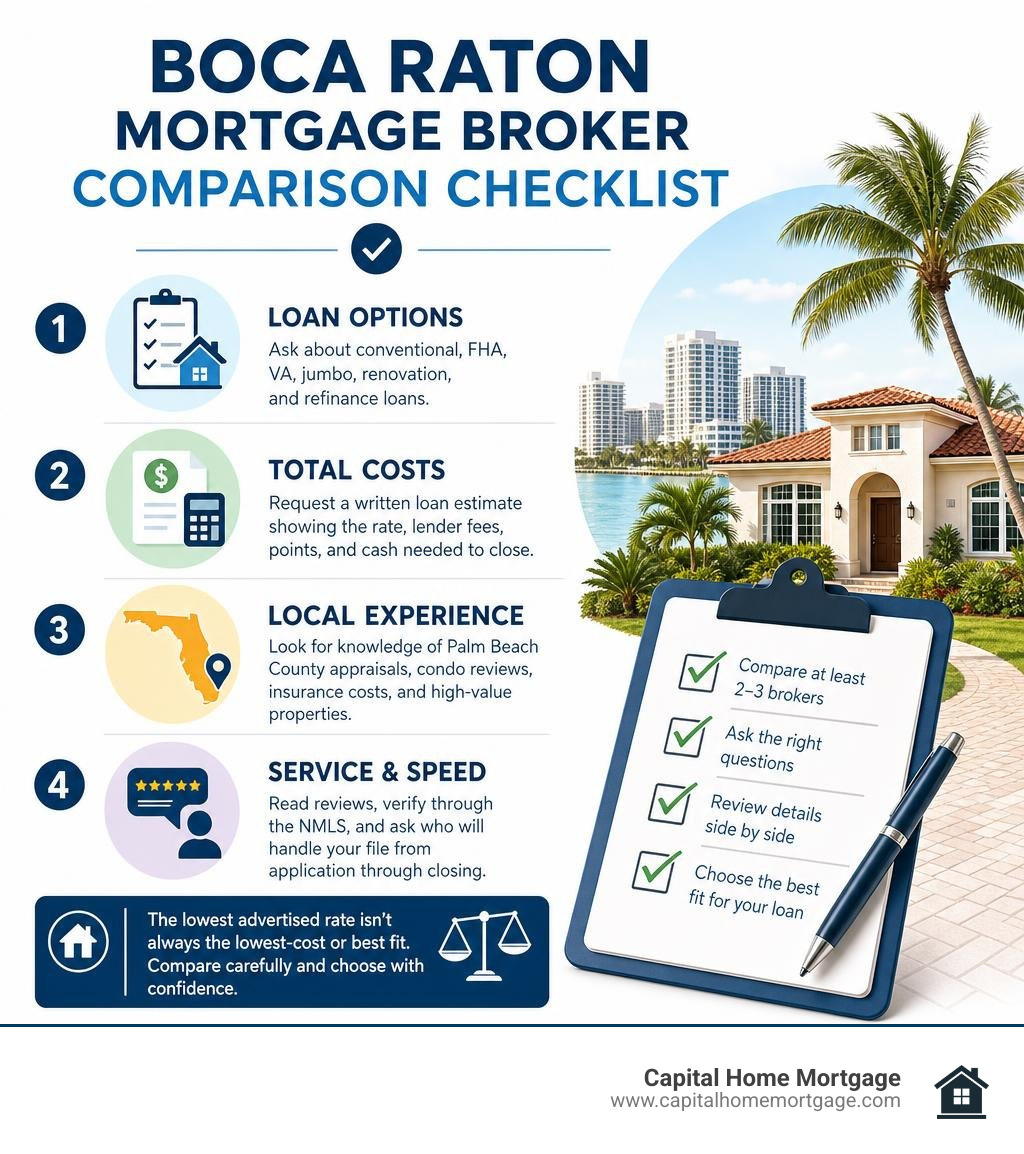
To find a strong fit among Boca Raton mortgage brokers, compare at least two or three professionals on the factors that affect your loan most:
- Loan options: Ask whether they offer conventional, FHA, VA, jumbo, renovation, and refinance loans.
- Total costs: Request a written loan estimate showing the rate, lender fees, points, and cash needed to close.
- Local experience: Look for knowledge of Palm Beach County appraisals, condo reviews, insurance costs, and high-value properties.
- Service and speed: Read recent reviews, verify the professional through the NMLS, and ask who will handle your file from application through closing.
The lowest advertised rate is not always the lowest-cost or best-fit mortgage. A clear lender or broker should explain your choices in plain language, help you compare payments and upfront costs, and provide a realistic closing timeline before you commit.
I am Dale Gremillion, a manager at Capital Home Mortgage with more than 26 years of experience in mortgage operations and client support. I work with Boca Raton mortgage brokers’ clients and homebuyers seeking purchase, refinance, FHA, VA, and jumbo financing with clear guidance from application to closing.
6 Core Loan Programs Offered by Boca Raton Mortgage Brokers
Finding a home in South Florida means navigating diverse property types, from gated golf communities and coastal high-rises to charming suburban neighborhoods. To make an offer that sellers respect, you need financing tailored to your exact scenario.

| Program | Best Suited For | Minimum Down Payment | Typical Credit Score Floor | Key Advantage |
|---|---|---|---|---|
| Conventional | Strong credit, stable income | 3% to 5% | 620 | Cancellable PMI, flexible terms |
| FHA Loans | Lower credit, smaller savings | 3.5% | 580 | Lenient debt-to-income limits |
| VA Loans | Active military, Veterans | 0% | 580 to 620 | No down payment, no monthly PMI |
| Jumbo Loans | Luxury & waterfront homes | 10% to 20% | 680 to 700+ | High borrowing limits above conforming caps |
| Renovation | Fixer-uppers, modernizing | 3.5% to 5% | 620 | Finance purchase and repairs together |
| Construction | Custom ground-up building | 10% to 20% | 680 | Single-close construction-to-permanent options |
Conforming and Government-Backed Purchase Loans
Conforming conventional loans serve as the backbone of residential real estate financing. These loans meet the standards set by Fannie Mae and Freddie Mac. When putting down at least 20%, you avoid private mortgage insurance (PMI) altogether, keeping your monthly housing payment lean.
For borrowers who need flexible credit underwriting or a lower barrier to entry, Florida FHA Home Loans allow down payments as low as 3.5% with credit scores starting around 580. FHA financing allows for higher debt-to-income (DTI) ratios, making it easier to purchase a home even if you have student debt or auto loans.
For active service members and veterans, Florida VA Home Loans offer an exceptional financing avenue:
- Zero down payment required on qualifying purchases
- No monthly private mortgage insurance premiums
- Competitive interest rates backed by government guarantees
- Capped closing fees to protect military families
High-Balance Luxury Financing and Jumbo Mortgages
Boca Raton is renowned for premier estates, private yacht basins, and world-class country clubs. Because local property values frequently exceed standard conforming loan limits, buyers rely heavily on Florida Jumbo Home Loans.
Underwriting luxury real estate requires specialized capabilities:
- Substantial Asset Reserves: Lenders often verify 6 to 12 months of post-closing principal, interest, taxes, and insurance (PITI) reserves.
- Complex Income Analysis: For entrepreneurs, investors, and high-earning professionals, we review K-1s, corporate returns, and liquid asset portfolios.
- Asset Depletion Options: High-net-worth retirees can leverage liquid investment accounts as qualifying income without liquidating their principal.
- Multi-Appraisal Reviews: Distinctive architectural features and waterfront access require experienced Palm Beach County luxury appraisers.
Specialized Renovation and Construction Financing
With limited vacant land along the coast, many buyers purchase existing properties in established neighborhoods and modernize them. Instead of taking out high-interest personal loans, you can bundle the acquisition and improvement costs through Florida Renovation Home Loans.
If you are planning a ground-up build on a private lot, Florida Construction Home Loans offer structured disbursement schedules. As building milestones are met, independent draw inspections verify progress before funds are released to licensed general contractors, protecting your investment from start to finish.
How to Evaluate and Select Local Mortgage Professionals
Securing the right loan structure can save you tens of thousands of dollars over the life of your mortgage. Understanding how your mortgage professional operates is the first step toward a smooth closing.

Vetting Boca Raton Mortgage Brokers via Local Reviews and Credentials
When evaluating local lending experts, verify their licensing via the Nationwide Multistate Licensing System (NMLS) Consumer Access database. This confirms that the loan officer has met state education, testing, and background standards.
Review genuine feedback by checking top local market directory reviews across Palm Beach County. Look for patterns in feedback:
- Consistent Communication: Does the team provide proactive weekly updates?
- Timeline Reliability: Are loans closing on or ahead of the contract date?
- Problem Resolution: How do they handle unexpected appraisal or title discrepancies?
Regional familiarity is critical in South Florida. Exploring insights from our Florida Category (West Palm Beach) team shows why local expertise matters when navigating condo associations, coastal windstorm requirements, and county tax prorations.
Critical Questions to Ask Boca Raton Mortgage Brokers Before Committing
Before signing an application or paying an appraisal deposit, ask these practical questions:
- “Are you a direct lender with in-house underwriting, or do you broker out your files?” Direct lenders maintain direct control over processing, underwriting, and closing documents, eliminating third-party bottlenecks.
- “What are your typical closing turnaround times?” While industry averages linger around 40 to 45 days, an efficient direct lender can close clean files in 21 to 30 days.
- “Do you offer rate-lock float-down options?” If market interest rates drop while your home is under contract, a float-down provision allows you to capture the lower rate.
- “Can you walk me through your complete fee breakdown?” Insist on reviewing standard loan estimates to compare origination points, processing charges, and third-party fees line by line.
The Boca Raton Home Financing Process from Application to Closing
Securing a mortgage involves an organized series of verification steps designed to protect both the buyer and the lender.
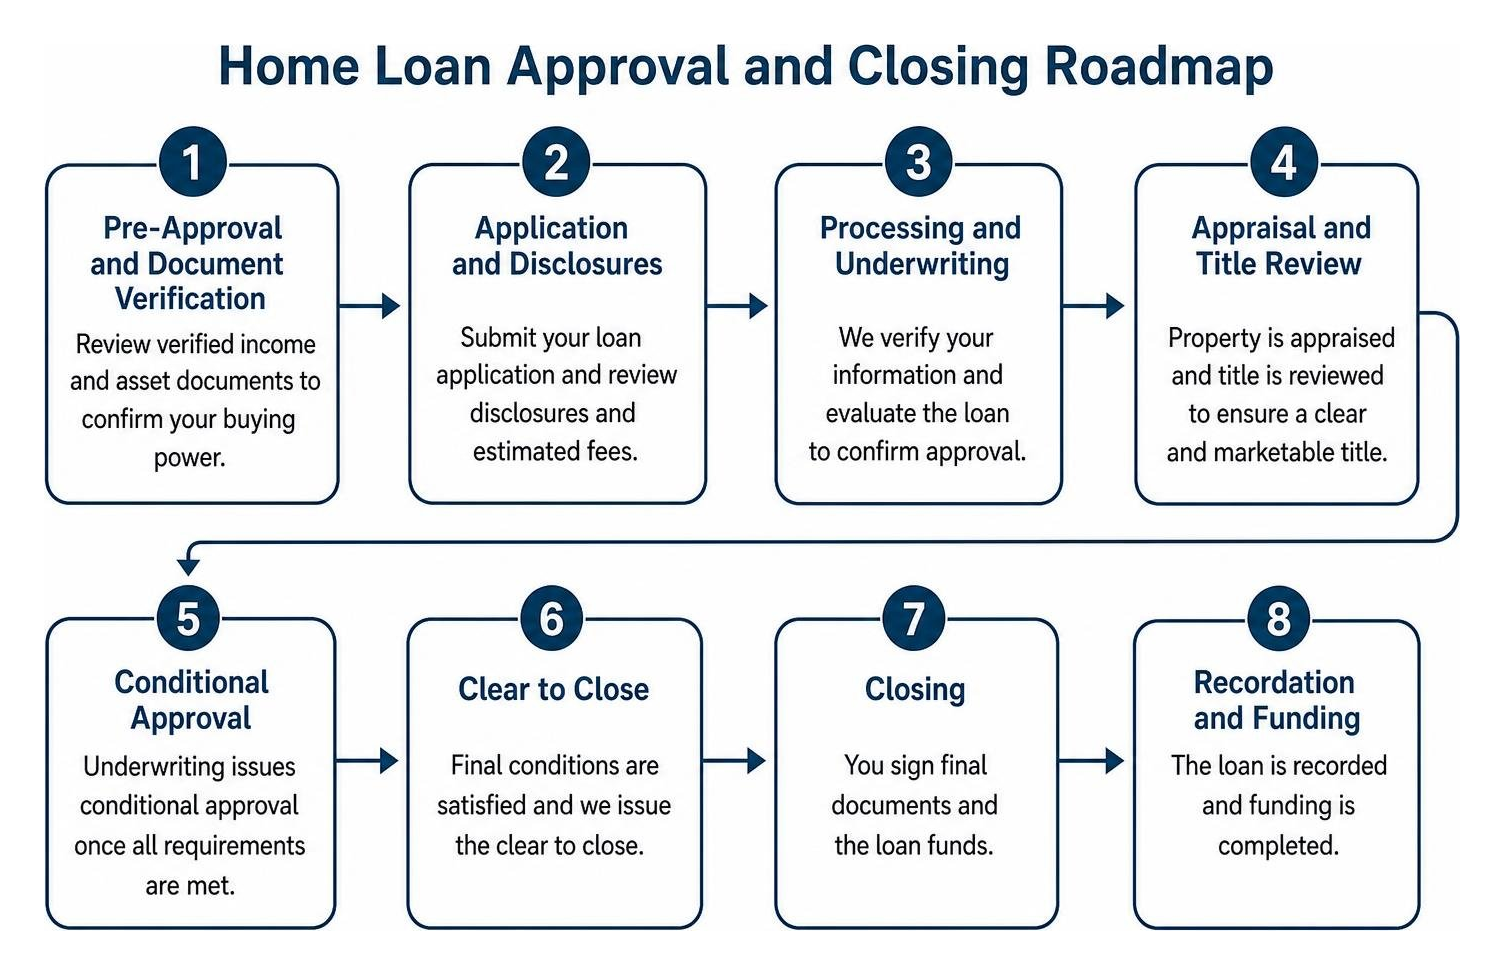
Pre-Approval and Documentation Verification
A pre-approval is far more substantial than an informal pre-qualification. We evaluate verified financial documents to ensure your buying power is rock-solid before you submit offers:
- Income Records: Two years of W-2s, 1099s, or complete personal and business tax returns
- Asset Statements: Two to three months of checking, savings, and investment account statements
- Credit Check: A comprehensive tri-merge credit report to assess your payment history and score
- Automated Underwriting System (AUS) Findings: Digital submission to Fannie Mae or Freddie Mac for baseline approval
With a formal pre-approval letter in hand, real estate agents and sellers will view your offer as equivalent to cash.
Property Appraisal and Underwriting
Once your purchase contract is executed, the underwriting team evaluates the property itself. In Palm Beach County, this involves specific local considerations:
- Appraisal Evaluation: An independent local appraiser inspects the property to verify that the fair market value supports the agreed purchase price.
- Condominium Questionnaire: If buying a condo, the Homeowners Association (HOA) must provide documentation regarding reserve funds, structural integrity inspections, and master insurance policies.
- Insurance Verification: Properties require windstorm mitigation inspections, hazard insurance policies, and potentially flood insurance if located in designated FEMA flood zones.
- Title and Lien Search: A licensed title agency reviews county municipal records to confirm clear ownership transfer without hidden encumbrances or unpermitted work.
Clear to Close and Loan Settlement
When all underwriting conditions are satisfied, your loan file receives the official Clear to Close (CTC).
By federal law, you will receive a Closing Disclosure (CD) at least three business days prior to loan consummation. This document details your finalized interest rate, monthly payment, and the exact wire transfer amount required for settlement. On closing day, you sign your mortgage note, the funds are wired, the deed is recorded, and you receive the keys to your new home.
Palm Beach County Refinancing and Home Equity Strategies
Mortgage planning doesn’t end when you purchase a property. As market conditions evolve and equity builds, refinancing serves as a powerful financial restructuring tool.
Rate-and-Term vs. Cash-Out Strategies
Depending on your financial goals, refinancing falls into two primary categories:
- Rate-and-Term Refinance: Focuses on reducing your monthly interest rate, shortening your loan term (such as moving from a 30-year to a 15-year mortgage), or eliminating monthly PMI once you have reached 20% home equity.
- Cash-Out Refinancing: Allows you to convert accrued home equity into liquid capital. Homeowners frequently use a Florida Cash-Out Mortgage Refinance to fund major home renovations, install impact-resistant windows, or eliminate high-interest revolving credit cards.
Senior Equity Solutions and Reverse Mortgages
For homeowners aged 62 and older who wish to eliminate their monthly mortgage payments and stay in their homes, Florida Reverse Mortgages provide a viable avenue.
A Home Equity Conversion Mortgage (HECM) allows senior homeowners to convert a portion of their home equity into tax-free cash flow, a flexible line of credit, or a lump-sum distribution. Borrowers remain on title and retain ownership, with no mandatory monthly mortgage payments required as long as property taxes, insurance, and maintenance obligations are fulfilled.
Frequently Asked Questions About Boca Raton Home Financing
What are the current mortgage rate trends in South Florida?
Mortgage interest rates are shaped by broader macroeconomic indicators, including Federal Reserve monetary policy, inflation data, and Treasury yields. In South Florida’s competitive real estate environment, buyers frequently utilize rate locks to protect against short-term market volatility during the escrow period. Choosing between a fixed-rate loan and an adjustable-rate mortgage (ARM) depends on how long you intend to own the property.
How do local brokers help first-time homebuyers qualify?
First-time buyers often believe they need a 20% down payment, but numerous state and federal programs make purchasing far more accessible. Local lending specialists connect buyers with competitive down payment assistance grants and flexible underwriting guidelines. Review our complete guide on how to qualify as a first-time home buyer in Florida to see how credit optimization and state bond programs can reduce your out-of-pocket entry costs.
How long does it take from pre-approval to closing in Palm Beach County?
A standard mortgage transaction typically takes between 21 and 30 days from signed contract to final closing. Working with a direct lender that handles underwriting and document preparation in-house prevents administrative delays. Promptly submitting your income documents, bank statements, and insurance binders helps ensure your loan closes on time without unnecessary extensions.
Secure Your South Florida Home Financing
Navigating the South Florida housing market requires direct access to experienced mortgage professionals who understand local property nuances. At Capital Home Mortgage, we operate as a direct, full-service mortgage lender, managing processing, underwriting, and closing coordination entirely under one roof.
Whether you are purchasing your first home, upgrading to a luxury waterfront property, or leveraging your home equity, our team delivers competitive terms and dedicated support at every step.
Explore your financing options today by reviewing our complete selection of Florida Home Purchase Loans or contacting our loan specialists to schedule your private mortgage consultation.


