
A 3% Down Payment Can Put Homeownership Within Reach
Conventional home loans with 3 down let eligible buyers finance up to 97% of a home’s price, so they may not need to wait until they have saved 20%.
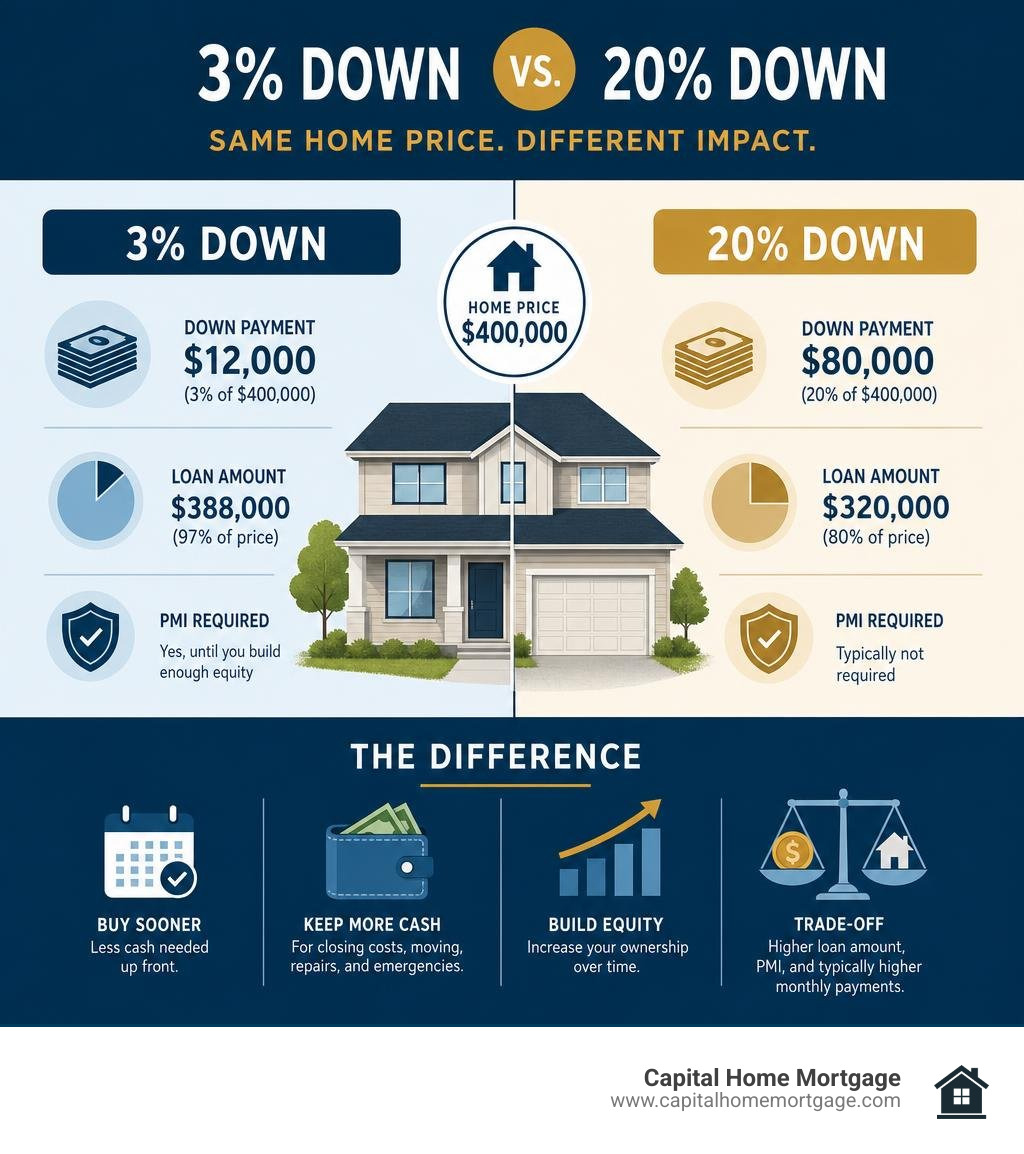
- On a $400,000 home, 3% down is $12,000. A 20% down payment is $80,000.
- On the September 2025 median existing-home price of $415,200, 3% equals $12,456, versus $83,000 at 20%.
- These are conventional mortgages, generally backed by Fannie Mae or Freddie Mac, and usually require private mortgage insurance (PMI) until you build enough equity.
- Buyers may qualify through programs such as Conventional 97, HomeReady, Home Possible, or HomeOne, depending on credit, income, property, and first-time buyer status.
A smaller down payment can help you buy sooner and keep more cash for closing costs, moving, repairs, and emergencies. The trade-off is a larger loan balance, PMI, and typically higher monthly housing costs than you would have with a larger down payment.
I’m Dale Gremillion, a manager at Capital Home Mortgage with more than 26 years of experience supporting buyers through conventional home loans with 3 down and other purchase financing options. In this guide, I’ll help make the main choices and costs easier to understand.
Understanding Conventional Home Loans With 3 Down
When people talk about conventional home loans with 3 down, they are referring to conventional mortgages structured with a maximum 97% loan-to-value (LTV) ratio. Unlike government-backed options like FHA, VA, or USDA mortgages, conventional loans are non-government loans that adhere to underwriting guidelines set by government-sponsored enterprises (GSEs)—specifically Fannie Mae and Freddie Mac.
These agencies buy mortgages from private lenders and wrap them into mortgage-backed securities, which injects liquidity into the housing market. To qualify for a 3% down payment conventional loan, the home’s purchase price must fall within conforming loan limits. In most parts of the country, the baseline single-family conforming loan limit is $806,500. In designated high-cost housing markets, that threshold increases up to $1,209,750.
Because putting down 3% leaves only 3% initial equity in the home, lenders face higher financial exposure if a default occurs. To offset this, private mortgage insurance (PMI) is required on conventional mortgages whenever the buyer puts down less than 20%. Understanding What Are 3% Down Mortgages? helps buyers see that PMI is simply an protection tool that allows lenders to extend low down payment options safely. If you are shopping in regions with dynamic housing markets, exploring options like Conventional Home Loans in Texas can give you a clear view of how these loan limits apply locally.
Qualification Guidelines for Conventional Home Loans With 3 Down
Qualifying for a 3% down conventional home loan requires meeting several baseline financial standards:
- Credit Score Requirements: The minimum credit score for 3% down conventional loans typically starts at 620. Higher scores—especially 670 to 740 and above—secure significantly lower interest rates and cheaper private mortgage insurance premiums.
- Debt-to-Income (DTI) Ratio: Lenders evaluate your total recurring monthly debt against your gross monthly income. While automated underwriting systems prefer a DTI ratio below 43%, ratios up to 45% or 50% can be approved with strong compensating factors like higher cash reserves or exceptional credit.
- Primary Residence Rule: Low down payment conventional options are strictly designed for primary residences. You cannot use a 3% down conventional loan to purchase an investment property or a second home.
- Income and Asset Verification: You must prove stable earnings through recent pay stubs, W-2 forms from the last two years, and recent tax returns. Your assets must be documented via two to three months of official bank statements to confirm you have cash for the 3% down payment plus closing costs.
Who Qualifies as a First-Time Homebuyer?
Many 3% down conventional programs require at least one occupant borrower to meet the formal definition of a “first-time homebuyer.” Under standard Fannie Mae and Freddie Mac guidelines, a first-time homebuyer is defined as any applicant who has not held an ownership interest in a primary residential property within the preceding three-year period.
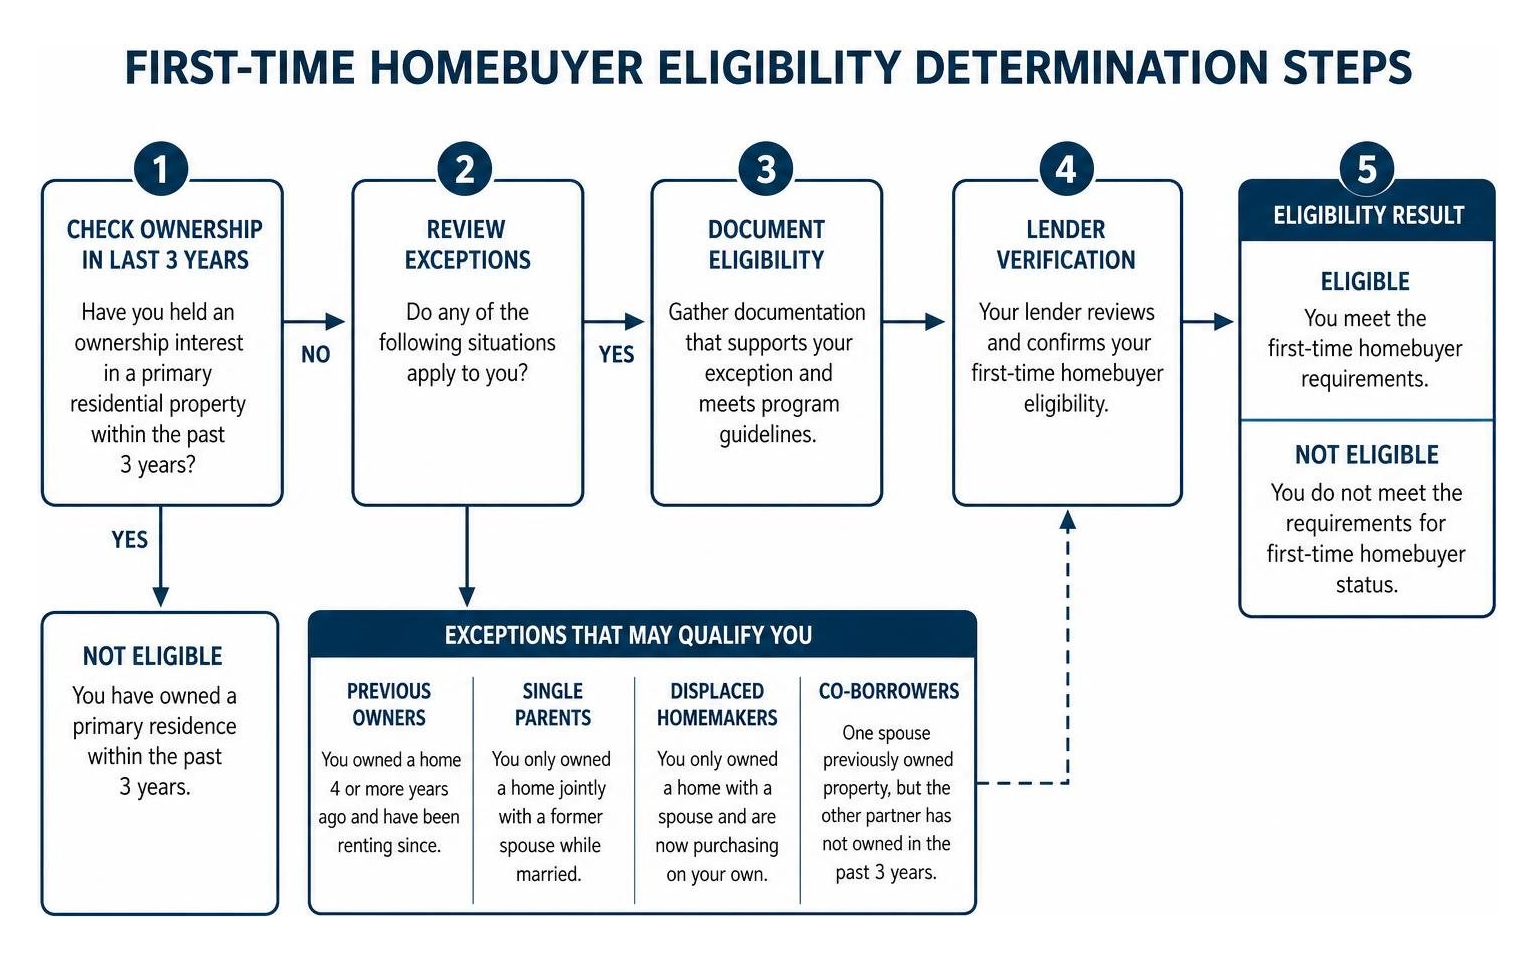
This definition is broader than many buyers realize. It includes:
- Previous Owners: Individuals who owned a home four or more years ago but have been renting since.
- Single Parents: A single parent who only previously owned a home jointly with a former spouse while married.
- Displaced Homemakers: Individuals who only owned a home with a spouse and are now looking to purchase on their own.
- Co-Borrowers: Couples where one spouse previously owned property, but the other partner has not owned a home in the past three years.
For standard Conventional 97 and HomeOne programs, only one qualifying borrower needs to meet this three-year rule, provided they complete an approved homebuyer education course when required.
Comparing Popular 3 Percent Down Mortgage Programs

Fannie Mae and Freddie Mac offer distinct 3% down loan products suited to different buyer profiles. Reviewing 3% Down Mortgages Open Homeownership Doors for More Buyers reveals how these specialized options cater to income levels, property types, and purchasing histories.
| Program Name | Backing GSE | First-Time Buyer Required? | Household Income Limits | Credit Score Minimum | Unique Features |
|---|---|---|---|---|---|
| Conventional 97 | Fannie Mae | Yes (at least one borrower) | No income caps | 620 | Standard 3% down option for single-family homes and eligible condos. |
| HomeOne | Freddie Mac | Yes (at least one borrower) | No income caps | 620 | Flexible option for single-family units; no geographical income restrictions. |
| HomeReady | Fannie Mae | No | Capped at 80% of Area Median Income (AMI) | 620 | Reduced PMI premiums; allows rental and boarder income for qualification. |
| Home Possible | Freddie Mac | No | Capped at 80% of Area Median Income (AMI) | 660 | Accepts non-occupant co-borrowers and sweat equity on single-unit homes. |
Standard Conventional 97 and HomeOne Programs
The Conventional 97 (backed by Fannie Mae) and HomeOne (backed by Freddie Mac) are baseline 3% down loan products designed for buyers who may earn too much income to qualify for assistance programs but want to minimize upfront costs.
Key characteristics include:
- First-Time Buyer Requirement: At least one borrower must meet the three-year non-ownership rule.
- Property Type Eligibility: Restricted primarily to 1-unit single-family detached homes, attached townhomes, and eligible Fannie Mae or Freddie Mac-approved condominiums. Standard manufactured housing is capped at 95% LTV unless categorized under specialized programs like MH Advantage.
- Loan Terms: Available with predictable 30-year fixed-rate mortgage terms.
- No Income Caps: Unlike specialized low-income programs, there are no ceilings on how much money you can earn to qualify.
Whether you are looking for home options through Conventional Home Loans in California or elsewhere, Conventional 97 and HomeOne offer reliable pathways into homeownership without income restrictions.
HomeReady and Home Possible Low-Income Programs
Fannie Mae’s HomeReady and Freddie Mac’s Home Possible programs target low- to moderate-income borrowers. The defining feature of both programs is that household income cannot exceed 80% of the Area Median Income (AMI) for the property’s specific census tract.
These targeted programs provide distinct advantages:
- No First-Time Buyer Requirement: You do not need to be a first-time buyer to use HomeReady or Home Possible, making them accessible to repeat buyers with modest incomes.
- Flexible Income Qualification: HomeReady allows you to count boarder income (rent from an individual who has lived with you for at least 12 months) or rental income from a multi-unit property (up to 4 units) toward qualification.
- Co-Borrowers and Grants: Home Possible permits non-occupant co-borrowers (e.g., parents co-signing for a child) to contribute toward the 3% down payment on single-unit properties.
- Discounted Private Mortgage Insurance: Qualified buyers receive reduced PMI coverage requirements—dropping standard 35% or 25% coverage requirements down to 25% for 97% LTV financing—significantly reducing monthly payments.
Pros, Cons, and Long-Term Costs of a 3 Percent Down Payment

Deciding on conventional home loans with 3 down involves weighing immediate access to housing against long-term carrying costs. Buyers exploring options like Conventional Home Loans in Tennessee often balance preserving cash for home improvements against paying higher monthly interest.
Pros of a 3% Down Payment:
- Faster Home Entry: You avoid waiting years to save an $80,000+ down payment while property values and rents continue rising.
- Preserved Liquidity: Keeping cash in the bank provides a safety cushion for emergencies, unexpected home repairs, or furniture purchases.
- Equity Appreciation: Owning a home allows you to capture full market appreciation on the entire value of the property, not just your 3% investment.
Cons of a 3% Down Payment:
- Mandatory PMI: You must pay monthly private mortgage insurance until your equity reaches 20%.
- Higher Monthly Payments: Financing 97% of the home price results in a higher principal loan balance, leading to larger monthly payments.
- More Lifetime Interest: Borrowing more money over a 30-year term means paying higher aggregate interest over the life of the loan.
Private Mortgage Insurance Costs and Cancellation Rules
Private mortgage insurance (PMI) is an ongoing fee that protects the lender if a borrower defaults. Unlike FHA loans, where mortgage insurance premiums (MIP) usually remain for the entire loan term, conventional PMI is temporary and flexible.
Key rules governing conventional PMI:
- Rates and Factors: Annual PMI costs typically range from 0.3% to 1.5% of the original loan balance per year, paid in monthly installments. Your exact rate depends on your credit score, DTI ratio, and loan program (HomeReady offers built-in PMI discounts).
- Cancellation at 80% LTV: Under the Homeowners Protection Act, you can formally request PMI cancellation once your loan principal balance reaches 80% of the home’s original appraised value. You can also request cancellation earlier if home appreciation builds your equity to 20%.
- Automatic Termination at 78% LTV: Lenders are legally required to automatically eliminate PMI once your principal balance reaches 78% of the original home value, provided your mortgage payments are current.
Impact on Monthly Mortgage Payments and Total Interest
To illustrate how a 3% down payment compares with a traditional 20% down payment, consider a home purchased at the national median price of $415,200 with an assumed interest rate of 6.5%:
- Option A (3% Down Payment):
- Down Payment: $12,456
- Starting Loan Balance: $402,744
- Estimated Principal & Interest: ~$2,546 / month
- Estimated Monthly PMI (at 0.75%): ~$252 / month
- Total Initial Housing Payment (P&I + PMI): ~$2,798 / month (excluding taxes/insurance)
- Option B (20% Down Payment):
- Down Payment: $83,000
- Starting Loan Balance: $332,160
- Estimated Principal & Interest: ~$2,099 / month
- Estimated Monthly PMI: $0
- Total Initial Housing Payment: ~$2,099 / month
Putting 3% down saves $70,544 in upfront cash but increases the monthly commitment by roughly $699 until PMI is canceled.
- Pros of Low Down Payment: Preserves liquidity, enables immediate purchase, lets you capture market appreciation early.
- Cons of Low Down Payment: Requires ongoing monthly PMI, higher loan balance leads to higher total interest over 30 years.
Alternatives to 3 Percent Down Conventional Financing
While conventional home loans with 3 down offer excellent structure, they are not the only low-down-payment options available. Homebuyers looking in specific local markets—such as those considering Conventional Home Loans in Charleston—frequently compare conventional options against government-backed loans or state assistance programs.
FHA vs. Conventional Low Down Payment Mortgages
FHA loans, insured by the Federal Housing Administration, are a primary alternative to conventional 3% down mortgages.
- Down Payment Requirements: Conventional loans allow 3% down, whereas standard FHA loans require a minimum of 3.5% down.
- Credit Score Flexibility: Conventional loans require a 620 minimum score. FHA loans allow down payments as low as 3.5% with credit scores down to 580 (or 10% down for scores between 500 and 579).
- Mortgage Insurance Comparison: Conventional loans require monthly PMI that can be canceled at 80% LTV. FHA loans require both an upfront mortgage insurance premium (1.75% of the loan amount) and an annual MIP fee that typically lasts for the entire 30-year term if you put down less than 10%.
- Underwriting Guidelines: FHA loans are more lenient regarding higher DTI ratios and recent credit setbacks, making them ideal for credit recovery.
VA, USDA, and Down Payment Assistance Options
Depending on your background, location, and income, zero-down-payment options may also be available:
- VA Loans: Guaranteed by the U.S. Department of Veterans Affairs, VA loans offer 0% down payment financing, no monthly mortgage insurance, and competitive interest rates for eligible military service members, veterans, and surviving spouses.
- USDA Loans: Backed by the U.S. Department of Agriculture, USDA loans provide 0% down financing for single-family homes located in designated rural and suburban areas, subject to household income caps.
- Down Payment Assistance (DPA) Programs: Many state and local housing finance authorities offer DPA grants, forgivable second loans, or low-interest loans that cover the required 3% down payment and closing costs. For example, buyers can explore state-specific resources like the Homebuyers Loan Program | CA Housing Finance Agency, the Time To Own Forgivable Down Payment Assistance | CHFA, or Homeownership Loans – State of Delaware to combine conventional low-down financing with regional grant support.
How to Apply for Conventional Home Loans With 3 Down
Applying for a 3% down conventional loan is a straightforward process, but getting organized ahead of time ensures quick processing. If you are starting your home search in areas like Conventional Home Loans in Spokane, proper preparation gives you a strong advantage when placing offers.
Step-by-Step Mortgage Preapproval Process
- Credit and Debt Check: Review your credit reports to fix errors, pay down revolving credit card balances, and ensure your FICO score meets or exceeds the 620 minimum threshold.
- Gather Income and Financial Documents: Compile essential paperwork, including:
- W-2s and 1099s from the past two years
- Federal tax returns from the past two years
- Recent pay stubs covering at least 30 consecutive days
- Bank and asset statements covering the past two to three months
- Submit Your Application: Work with our dedicated loan officers to complete your formal mortgage application. We run your profile through Fannie Mae’s Desktop Underwriter (DU) or Freddie Mac’s Loan Product Advisor (LPA) to get automated underwriting approval.
- Obtain Your Preapproval Letter: Receive a strong preapproval letter detailing your maximum purchase power, giving sellers complete confidence in your offer.
Completing Homebuyer Education Requirements
If all occupant borrowers on a standard Conventional 97, HomeOne, or HomeReady purchase loan are first-time homebuyers, at least one borrower must complete an approved homebuyer education course before closing.
- Approved Courses: Fannie Mae offers an online education platform called HomeView, which fulfills the requirement free of charge. Courses from HUD-approved housing counseling agencies are also accepted.
- Course Topics: The education modules cover budgeting, credit management, understanding mortgage terms, home maintenance responsibilities, and avoiding default.
- Timing: Complete the course early in the purchasing process to receive your official completion certificate, which is required prior to clear-to-close loan sign-off.
Frequently Asked Questions About 3 Percent Down Mortgages
Can you get a 3 percent down conventional loan with a 620 credit score?
Yes, a 620 FICO score is the official minimum threshold for standard conventional 3% down payment programs like Conventional 97 and HomeReady. However, keep in mind that borrowers with credit scores closer to 620 may face higher interest rates and elevated monthly PMI premiums compared to applicants with scores above 720.
Do 3 percent down conventional loans have higher interest rates than 20 percent down loans?
Typically, yes. Because lenders absorb higher risk when financing 97% of a home’s purchase price, base interest rates on 3% down mortgages can be slightly higher than rates for loans with 20% down payments. However, qualifications through programs like HomeReady can reduce or waive certain risk-based price adjustments, helping keep rates very competitive.
Can down payment assistance cover the full 3 percent down payment requirement?
Yes. Fannie Mae and Freddie Mac allow the required 3% down payment to come entirely from eligible gift funds (from family or documented relatives), employer assistance grants, or structured Community Seconds subordinate loans provided by approved government or non-profit down payment assistance programs.
Conclusion
Navigating conventional home loans with 3 down does not have to be overwhelming. Putting down 3% allows you to enter the real estate market sooner, start building equity, and keep your hard-earned liquid savings intact for life’s unexpected events.
At Capital Home Mortgage, we are a direct mortgage lender offering complete in-house processing and underwriting. Our direct structure allows us to deliver quick preapprovals, competitive interest rates, and on-time closings backed by dedicated loan officer guidance every step of the way. If you are ready to explore low down payment options tailored to your income, credit profile, and homeownership goals, contact our experienced originators today or explore our regional solutions at Conventional Home Loans in Texas to get started.


