
What Is an FHA 203k Full Loan — and Which Option Is Right for You?
The FHA 203k full loan — officially called the Standard 203(k) — lets you buy and renovate a home using a single mortgage. Instead of juggling a purchase loan plus a separate home improvement loan, you roll both into one FHA-insured product.
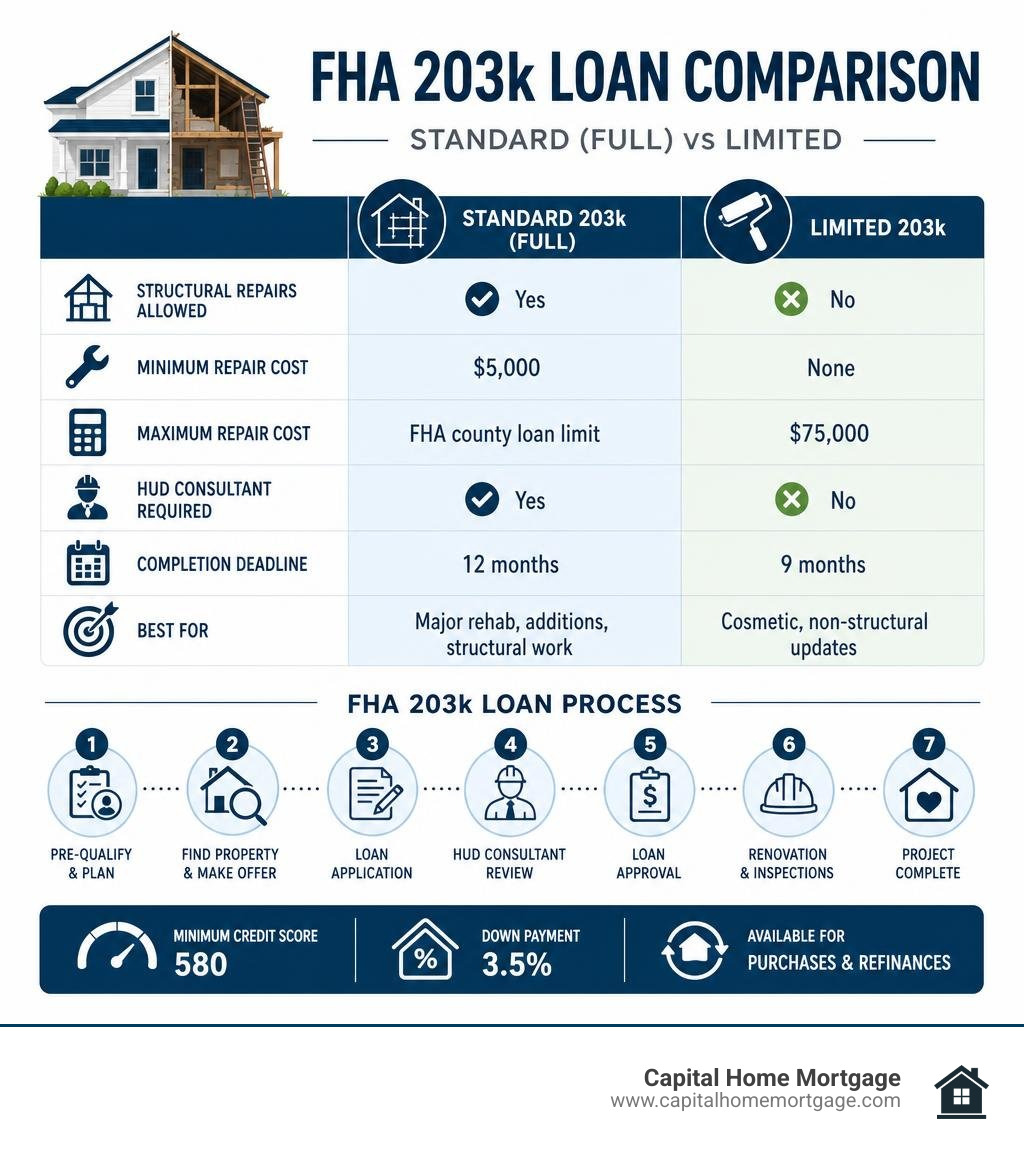
Here’s a quick comparison so you can see which version fits your project:
| Feature | Standard 203k (Full) | Limited 203k |
|---|---|---|
| Structural repairs allowed | Yes | No |
| Minimum repair cost | $5,000 | None |
| Maximum repair cost | FHA county loan limit | $75,000 |
| HUD consultant required | Yes | No |
| Completion deadline | 12 months | 9 months |
| Best for | Major rehab, additions, structural work | Cosmetic, non-structural updates |
The short answer: If your project involves structural changes — like foundation work, load-bearing walls, or major additions — you need the Standard 203k full loan. If it’s cosmetic work only, the Limited 203k is simpler and faster.
Both versions are available for purchases and refinances on eligible properties, with a minimum credit score of 580 and a 3.5% down payment.
I’m Dale Gremillion, a Manager at Capital Home Mortgage with over 26 years of experience helping homebuyers navigate specialized programs like the FHA 203k full loan. In this guide, I’ll walk you through everything — eligibility, eligible repairs, costs, and the step-by-step process — so you can move forward with confidence.
What Is an FHA 203k Full Loan and How Does It Compare to Limited 203k?
When you stumble upon a property with incredible potential but a roof that looks like it barely survived a cannonball test, standard home loans won’t work. Most traditional mortgages require a home to meet strict safety and habitability guidelines before closing. That’s where the Federal Housing Administration step in with the Section 203(k) Rehabilitation Mortgage Insurance Program.
The program comes in two distinct flavors: the FHA 203k full loan (officially called the Standard 203k) and the Limited 203k (formerly known as the Streamline 203k). Knowing which one matches your project scope is the very first crossroads you will face.
| Program Feature | Standard 203(k) Full Loan | Limited 203(k) Loan |
|---|---|---|
| Primary Focus | Major structural alterations & extensive rehab | Minor updates & non-structural repairs |
| Minimum Repair Amount | $5,000 | No minimum |
| Maximum Repair Cap | Capped only by FHA county loan limits | $75,000 maximum cap |
| Required Oversite | Mandatory HUD-approved 203(k) Consultant | Consultant optional; contractor bids only |
| Structural Changes | Allowed (foundations, additions, load-bearing) | Strictly Prohibited |
| Displacement Cover | Up to 6 months mortgage payments financeable | Not available |
| Completion Timeframe | Within 12 months of closing | Within 9 months of closing |
Structural Improvements vs. Cosmetic Repairs
The fundamental difference between these two products hinges entirely on structural alterations.
If your project involves cutting into load-bearing walls, replacing a failing foundation, adding a room, or reconstructing a structure on an existing foundation, you are required to use an FHA 203k full loan. In fact, HUD guidelines allow you to rebuild a home entirely from the ground up, provided the original foundation system remains intact and is fully reused.
On the flip side, the Limited 203k is tailored for minor, non-structural upgrades. Think of it as the interior designer’s delight: repainting, upgrading kitchen cabinets, installing new carpeting, replacing roof shingles, or updating plumbing fixtures without moving supply lines around. If you want to dive deeper into official government program distinctions, you can review the 203(k) Rehabilitation Mortgage Insurance Program Types documentation.
Repair Limits, Timelines, and Consultant Requirements
Beyond structural changes, project math dictates your loan choice. The FHA 203k full loan requires a minimum repair budget of $5,000. There is no hard dollar ceiling on the repair budget itself, provided the total combined loan (purchase price plus renovation costs) remains within the FHA maximum loan limit for the county.
For the Limited 203k, eligible non-structural repairs are capped at $75,000 (applicable for FHA Case Numbers assigned on or after November 4, 2024).
The Standard 203k requires an independent HUD 203(k) consultant selected by your lender from the official HUD roster. This consultant acts as project project manager, preparing an initial feasibility study, detailed work write-up, cost estimates, and supervising step-by-step contractor draw requests.
Finally, time horizons differ slightly: work financed through a Standard 203k full loan must be completed within 12 months of loan closing, whereas Limited projects must be finished within 9 months.
How to Qualify for Renovation Financing
Qualifying for an FHA 203k full loan follows the base guidelines of standard FHA mortgage underwriting, with a few extra layers related to construction feasibility and total borrowing ratios.

Eligibility Rules for an FHA 203k Full Loan
Because FHA loans are designed to broaden homeownership access, qualification standards remain very flexible compared to private construction loans:
- Credit Score & Down Payment: You need a minimum credit score of 580 to qualify for the low down payment option of 3.5%. If your credit score falls between 500 and 579, you can still qualify, but FHA guidelines require a 10% down payment.
- Debt-to-Income (DTI) Ratios: Your total monthly debt obligations (including the new mortgage payment) should ideally not exceed 43% of your gross monthly income. However, automated underwriting approvals can sometimes stretch higher with strong compensating factors.
- Occupancy Requirements: The property must be your primary residence. Investors looking to flip houses are not eligible for 203(k) financing.
- Down Payment Math: Your 3.5% down payment is calculated based on the total project cost — meaning the purchase price plus total renovation costs — rather than just the initial purchase price.
If you are exploring property options in the Lone Star State, our specialized guidance on Texas Renovation Home Loans can help you structure your down payment calculations effectively.
Property Types, Minimum Standards, and Refinancing Guidelines
The FHA 203k full loan can be used on several property types, provided they have been completed and occupied for at least one year prior:
- Single-family detached homes
- 2-to-4 unit multi-family properties (where you live in one unit and rent the others)
- Approved condominiums (limited to interior renovations only)
- Townhomes
- Manufactured homes titled as real estate
- Mixed-use properties, provided that at least 51% of the total square footage is dedicated strictly to residential living space
Every project must result in a home that satisfies FHA Minimum Property Requirements (MPR) upon completion. That means fixing any structural defects, health risks, lead-based paint, broken heating systems, or damaged electrical systems takes top priority before cosmetic upgrades can be funded. To better understand how low down payments work alongside FHA safety guidelines, check out our guide on How An FHA Affordable Housing Mortgage Can Buy Your First Home.
Eligible Repairs, Costs, and Maximum Loan Calculations
When mapping out your dream project under an FHA 203k full loan, understanding what HUD allows (and strictly forbids) will keep your renovation budget on track.
Allowed Rehabilitation Projects vs. Restricted Luxury Upgrades
The Standard 203k is remarkably versatile. Allowed improvements include:
- Structural alterations, additions, and complete foundation replacement
- Major plumbing, electrical, and HVAC overhaul
- Roof, gutter, and downspout replacements
- Major kitchen and bathroom redesigns
- Major structural flooring repairs and subfloor installation
- Accessibility enhancements for elderly or disabled residents
- Site improvements, grading, and walkway replacements
- Repairing or eliminating health and safety hazards (such as mold or lead remediation)
However, FHA guidelines draw a firm line at luxury enhancements. You cannot use 203(k) funds to build a outdoor swimming pool, add an outdoor gazebo, build an outdoor fireplace, or construct tennis courts. If a property already has a damaged pool, you can use 203(k) funds to fill it in or repair it to meet safety codes, but you cannot construct a new one. For a detailed breakdown of official borrower processing guidelines, review Processing a Mortgage for FHA Insurance.
Calculating Base Mortgage, Fees, and Reserve Funds
Calculating your maximum borrowing amount involves looking at both the acquisition costs and the “after-improved” appraised value of the home.
The maximum base mortgage amount is determined by taking the lesser of:
- The purchase price plus total renovation costs (including fees and contingency funds).
- 110% of the after-improved appraised value (100% for condominiums).
In 2026, the baseline FHA single-family loan limit in low-cost counties stands at $541,287, while high-cost markets can reach up to $1,249,125.
Inside this calculation, several administrative costs are neatly rolled into the overall loan balance:
- Contingency Reserve Fund: FHA mandates a contingency reserve between 10% and 20% of financeable repair costs to cover unexpected structural surprises once walls are opened up. Unused contingency funds are applied directly back toward your loan principal upon project completion.
- Financeable Origination Fees: Lenders can charge a supplemental origination fee on 203(k) projects, capped at the greater of $350 or 1.5% of the total repair costs and reserves.
- Mortgage Payment Reserve: If the home will be completely uninhabitable during structural renovations, an FHA 203k full loan allows you to finance up to 6 months of mortgage payments (PITI) into the loan balance so you aren’t paying a mortgage and rent simultaneously.
For borrowers looking to finance projects on the West Coast, explore our page on California Renovation Home Loans for local insights.
Step-by-Step Renovation and Loan Disbursement Process

A Standard 203k renovation requires careful coordination between you, your lender, your HUD consultant, and your contractor. Here is how the process flows from initial application to final nail.
Navigating the Application Process for an FHA 203k Full Loan
- Pre-Approval: Apply with a dedicated lender like Capital Home Mortgage to confirm your credit, income, and overall borrowing budget.
- Consultant Site Visit: Once you find a house, a licensed HUD 203(k) consultant visits the property to perform a detailed feasibility study and write up the official scope of work.
- Contractor Bids: You hire a fully licensed and insured general contractor who submits a detailed, line-itemed estimate based directly on the consultant’s work write-up.
- Appraisal Evaluation: An FHA appraiser evaluates the property blueprints and write-up to calculate the property’s estimated “after-improved value.”
- Underwriting & Closing: Our in-house underwriting team reviews the structural plans, credit profile, and appraisal. Once approved, the loan closes, purchase funds are paid to the seller, and renovation funds are placed into an escrow trust account.
For more information on navigating early application stages, consult FHA 203(k) Loan Details.
Managing Contractors, Inspections, and Payout Schedules
Once the loan closes, construction can officially commence.

Unlike standard loans where contractors demand big upfront cash payments, 203(k) renovation money is disbursed gradually out of the escrow account. For a Standard 203k full loan, the disbursement process follows strict structural draw milestones:
- Up to 5 list draws are permitted as distinct phases of work are completed.
- A initial draw at closing can release up to 50% of material costs for custom items ordered in advance (such as custom cabinets or windows).
- As each phase is finished, the HUD consultant performs a site inspection to confirm work quality and code compliance.
- Once approved, a two-party check is issued jointly to both you and your general contractor. This ensures no money changes hands until you verify the work is done right.
- Upon full completion, a final inspection is performed, final lien waivers are signed, and a completion letter releases the remaining escrow funds.
If you are planning a rehab project in the Sunshine State, visit our dedicated page on Florida Renovation Home Loans to see how local building guidelines integrate with FHA draw schedules.
Frequently Asked Questions About FHA 203k Loans
Can I perform DIY work with an FHA 203k loan?
Generally, no. HUD requires all work on an FHA 203k full loan to be completed by licensed, insured, and experienced general contractors. Self-performed “sweat equity” is restricted. You can only perform DIY work if you are a licensed professional contractor by trade and approved by the lender’s underwriting department. Even then, you can only finance the raw cost of materials — you cannot bill for your own labor.
How do energy-efficient upgrades integrate with 203k financing?
You can combine an FHA 203k full loan with the FHA Energy Efficient Mortgage (EEM) program or solar/wind additions. Financing energy-saving improvements like high-efficiency HVAC units, air sealing, upgraded insulation, or solar panels allows you to wrap additional funds into your mortgage. Solar and wind technology additions can increase the base mortgage amount by up to 20% of the home’s after-improved value.
What happens if unexpected renovation costs arise?
Unexpected structural problems are common when working on older fixer-uppers. That is exactly why the mandatory contingency reserve fund (10% to 20%) is built into your base loan amount. If your contractor uncovers hidden wiring defects or rotten subflooring, the consultant submits a formal change-order request to release funds from your contingency reserve. If you complete the entire project without touching your contingency reserve, those extra funds are applied straight to your principal loan balance, instantly increasing your home equity.
Conclusion
Restoring a distressed house or turning an outdated fixer-upper into your dream home does not require juggling high-interest credit cards, personal loans, or secondary construction financing. With an FHA 203k full loan, you get a single loan, a single monthly payment, and competitive fixed interest rates backed by the FHA.
While the process requires careful planning, working with an experienced lender makes all the difference. At Capital Home Mortgage, our direct, full-service model features complete in-house processing and underwriting. That means your loan stays under one roof, providing faster approvals, direct answers, and on-time closings without third-party delays.
Whether you are looking to purchase a home that needs major structural work or refinance your existing home to rebuild its foundation, our dedicated mortgage specialists are ready to guide you step-by-step. Ready to explore your renovation financing options? Explore Capital Home Mortgage Renovation Solutions or call us today to get started!


