
How a Construction Loan into Mortgage Conversion Works
When you decide to build a custom house, managing short-term construction expenses and long-term home debt requires a clear strategy. Navigating how a construction loan into mortgage process transitions depends primarily on whether your loan structure uses a single-close or a two-close framework.
With a single-close loan (often referred to as a construction-to-permanent loan), interim financing and your permanent 30-year mortgage are wrapped into one legal agreement executed before ground is broken. During the building phase, your lender disburses funds directly to your builder based on pre-approved draw schedules. You generally make interest-only payments on the money actually drawn out. Once the home passes its final inspection and receives a certificate of occupancy, the balance automatically transitions into standard principal and interest payments without requiring you to attend a second closing or pay additional settlement fees.
By contrast, a two-close process keeps interim construction financing completely separate from long-term home debt. You secure a short-term construction loan from a bank or private lender to pay the builder. Once the home is built, you must apply for a completely new permanent home loan to pay off that original construction debt.
For borrowers aiming to streamline their path to ownership, single-close options reduce paperwork and insulate against rising interest rates. According to official Fannie Mae Selling Guide Rules, single-closing transactions are designed as temporary construction financing exempt from standard Regulation Z Ability-to-Repay requirements during the build phase, automatically shifting into fixed long-term amortization terms post-completion.
Stand-Alone Construction Loans vs. Construction-to-Permanent Financing
Understanding the distinct features of stand-alone construction loans versus single-close construction-to-permanent financing can save you thousands of dollars and prevent unexpected headaches down the road.
A stand-alone construction loan strictly covers the build phase—typically 12 months. It offers maximum interim flexibility if you are unsure who your final mortgage lender will be, but it carries significant risk:
- Secondary Closing Costs: You must pay two separate sets of closing fees, title insurance premiums, and lender origination charges.
- Requalification Risk: If you lose your job, experience a drop in credit score, or accumulate extra debt during construction, you might fail to qualify for the permanent mortgage required to pay off the interim loan.
- Interest Rate Uncertainty: You cannot lock in long-term fixed interest rates until the home is nearly finished, leaving you exposed to market fluctuations.
Conversely, construction-to-permanent financing removes these secondary risks by establishing your long-term interest rate, loan terms, and underwriting approvals up front before a single nail is driven.
The Mechanics of Automatic Loan Conversion
How does an interim build line actually convert into a traditional 30-year loan? The mechanism relies on pre-signed legal documents. When you close on a single-turn loan, you sign the primary promissory note alongside either a Construction Loan Rider (Option 1) or a Loan Modification Agreement (Option 2).
During the construction window, funds are released in phases as completed stages pass third-party physical inspections. While work is underway, you only pay monthly interim interest on the exact amount disbursed. Once construction ends, a final Appraisal Update and Completion Report (Form 1004D) verifies that the home was built to the original plans and specifications.
Upon signing the final conversion documentation or activating the rider, your temporary interest-only phase ends. The principal balance converts automatically into a fully amortizing, long-term loan structure (typically a 15-year or 30-year term), establishing regular monthly principal and interest payments.
Qualification Rules and Guidelines for Custom Build Financing
Qualifying for custom build financing is slightly more involved than getting a standard home purchase mortgage. Because lenders take on the risk of funding an unbuilt structure, they evaluate both your personal finances and your builder’s qualifications.
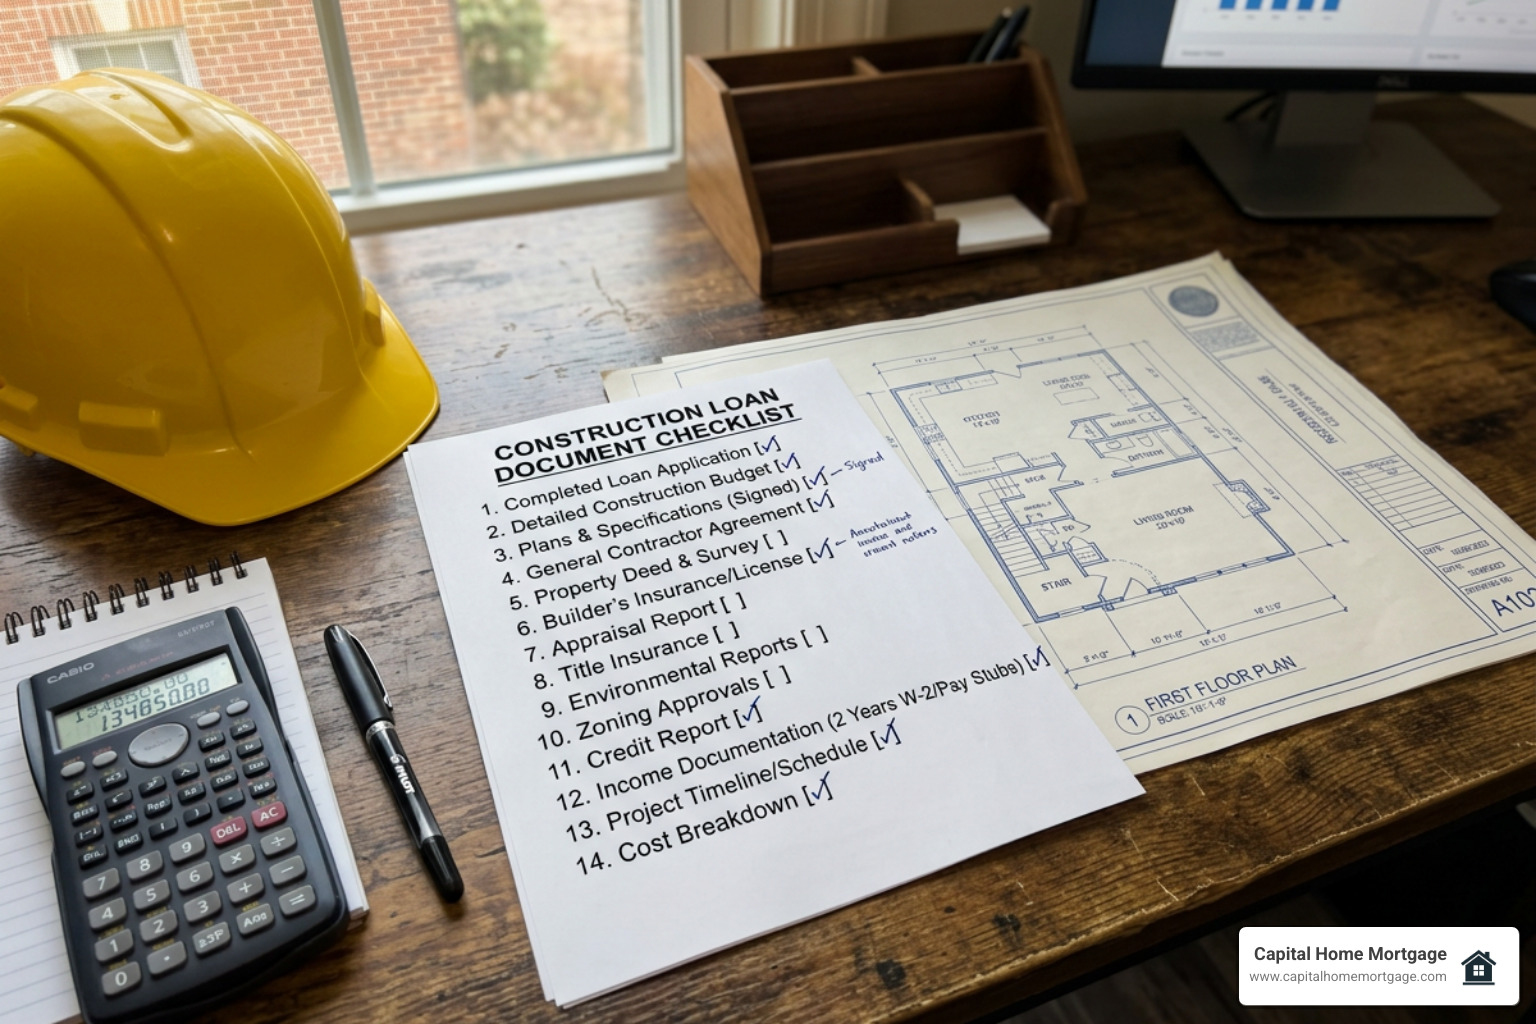
Lenders evaluate key financial metrics:
- Credit Score: Minimum thresholds range from 620 for government-backed products to 680 or higher for conventional custom builds.
- Debt-to-Income (DTI) Ratio: Your total monthly debt obligations (including your future mortgage payment) should generally fall under 45%, though government programs permit DTI ratios up to 50% in qualifying scenarios.
- Down Payment and Assets: Requirements vary from 0% down for eligible VA loans to 3.5% for FHA builds and 5% to 20% for conventional construction options.
- Builder Vetting: Your general contractor must submit proof of licensing, liability insurance, trade references, and a clean financial track record.
Qualifying to Turn a Construction Loan into Mortgage Terms
Your credit score and cash reserves largely dictate the type of construction-to-permanent loan program you can access. For instance, conventional custom build programs often look for credit scores starting at 680 along with a 20% down payment, though some lender programs permit down payments as low as 5% with a minimum 620 credit score.
If you are evaluating options in specific states, regional program details can impact your timeline. Check out our comprehensive guide on how to qualify for a construction loan in Florida to see localized builder review standards and regional qualification steps.
To keep your qualification intact while turning a construction loan into mortgage status:
- Avoid changing jobs or taking on new debt (such as financing a vehicle) during the build.
- Keep bank statements and financial records up to date.
- Reserve extra emergency funds beyond your required down payment to absorb potential construction budget overruns.
Calculating LTV Ratios: Owning Your Lot vs. Purchasing Land
Loan-to-Value (LTV) calculations for construction financing depend on whether you already own the building site or are buying the land and financing the build simultaneously.
- When Buying Land and Building Simultaneously: The LTV ratio is calculated using the total purchase cost—the acquisition price of the lot plus total documented construction costs—or the “as-completed” appraised market value, whichever figure is lower.
- When Building on Land You Already Own: LTV is determined by dividing the proposed loan amount by the “as-completed” appraised market value of the land and future structure combined.
If you already hold title to the lot, equity in the land can count directly toward your down payment requirement. For example, if your land is valued at $80,000 with no existing liens, that $80,000 is recognized as equity, potentially satisfying a 20% down payment requirement on a $400,000 total project cost without additional cash out of pocket.
Program Options for Government and Conventional Construction Financing
Choosing the proper loan program affects your down payment, interest rates, and ongoing mortgage insurance rules. Government-backed options allow lower down payments and flexible credit guidelines, while conventional construction financing offers higher loan limits and flexible post-construction terms.
| Feature | FHA One-Time Close | VA Construction | USDA Construction | Conventional Single-Close |
|---|---|---|---|---|
| Minimum Credit Score | 620 | 620 (typical lender min) | 640 | 620 – 680 |
| Minimum Down Payment | 3.5% | 0% | 0% | 5% – 20% |
| Max DTI Ratio | Up to 50% | Flexible | 41% (flexible with manual) | 45% |
| Eligible Property Types | Stick-built, modular, doublewide manufactured | Stick-built, modular | Stick-built, modular | Stick-built, modular |
| Payments During Build | None required (varies by lender) | Interest-only / builder funded | Interest-only | Interest-only on drawn funds |
FHA One-Time Close: Turning an FHA Construction Loan into Mortgage Protection
An FHA One-Time Close loan is an appealing option for buyers seeking manageable down payments and lenient credit terms. It allows qualifying borrowers to secure land, fund construction, and lock in a permanent FHA-insured mortgage with a single closing.
Key program benefits include:
- A low down payment requirement of 3.5%.
- Minimum qualifying credit score of 620.
- Debt-to-income limits allowed up to 50% with strong compensating factors.
- Land equity credited directly toward down payment needs.
- Flexible property guidelines accepting single-family stick-built homes, modular units, and new doublewide manufactured homes (singlewide and multi-family structures are excluded).
In many FHA One-Time Close structures, no mortgage payments are due from the borrower during active construction, easing financial pressure while you await move-in day. If you live in the Southwest, review our breakdown on how one-time construction loans work in Arizona to understand regional processing timelines.
Comparing VA, USDA, and Conventional Single-Close Options
Beyond FHA options, government and conventional single-close products address distinct financial scenarios:
- VA Construction Loans: Available to eligible military service members, veterans, and surviving spouses, offering a 0% down payment option, no monthly mortgage insurance (PMI), and competitive interest rates.
- USDA Construction Loans: Tailored for low- to moderate-income buyers building in designated rural zones, featuring 0% down payment options and competitive long-term fixed rates.
- Conventional Single-Close Loans: Ideal for borrowers with higher credit scores (680+) and larger down payments (5% to 20%). Conventional programs provide straightforward rate locks and eliminate private mortgage insurance once home equity reaches 20%.
For further technical reading on Fannie Mae guidelines, browse Homebuyer.com Construction Guidelines for standard secondary market framework rules.
Construction Timelines, Appraisals, and Handling Cost Overruns
Managing construction timelines and keeping financial documentation up to date are essential steps in turning a construction loan into mortgage status smoothly. Lenders enforce strict operational windows to ensure custom home projects are finished promptly and within budget.
Construction Period Limits, Document Rules, and Form 1004D
Under conventional Fannie Mae single-closing rules, total construction timelines are strictly limited:
- The interim build window cannot exceed 18 months total.
- No individual construction draw phase may exceed 12 months without formal extension updates.
- Credit and income documents must be no more than 4 months old on the note date (the initial loan closing).
However, an important exception applies: if your loan achieves a Desktop Underwriter (DU) Approve/Eligible recommendation and has a Loan-to-Value (LTV) ratio of 95% or lower at initial closing, credit documents can remain valid for up to 18 months at final conversion without requiring full re-underwriting.
When building wraps up, an inspector or appraiser completes an Appraisal Update and Completion Report (Form 1004D). This report confirms the home matches the initial construction plans and verifies its final value for long-term mortgage backing.
Managing Build Delays, Builder Overruns, and Requalification Risks
Custom builds can experience unexpected supply chain delays, weather challenges, or material price increases. Handling these hurdles effectively keeps your loan conversion on schedule.
When unexpected issues arise:
- Change Orders: Any floor plan modification or material upgrade requires a formal change order signed by you, the builder, and the lender.
- Budget Overruns: Uncovered cost overruns must either be paid out of pocket or incorporated into an approved loan amount modification before final conversion. Minor loan modifications (up to $5,000 or 2% of the original loan balance) are generally allowed without full re-underwriting.
- Requalification Triggers: Major build delays stretching past 18 months, significant interest rate increases, or major changes to your personal credit profile can trigger full requalification.
Partnering with an experienced lender helps manage these moving parts effectively. Take time to read our detailed guide on finding the right lender to build your dream home from scratch.
Weighing the Pros and Cons of Single-Close Build Financing
While single-close construction-to-permanent financing offers a convenient path to custom ownership, assessing both advantages and limitations ensures you choose the right approach for your project.
Advantages of Single-Closing Financing
- Reduced Closing Costs: You pay settlement fees, legal costs, title charges, and underwriting fees once, saving thousands compared to a two-close process.
- Protection Against Rising Rates: Your long-term mortgage interest rate is fixed before construction starts, keeping your future payments predictable.
- Simplified Application: You complete one initial loan application and credit check, eliminating mid-project paperwork strain.
- No Post-Build Requalification: Provided construction stays within standard timeframe limits and guidelines, you will not face additional credit checks after move-in.
Disadvantages and Potential Pitfalls
- Strict Structural Rules: Changes to floor plans, construction timelines, or material budgets require formal lender approval.
- Stricter Qualification Standards: Combining two loan types into one upfront closing means lenders enforce rigorous initial credit, income, and builder vetting reviews.
- Time Window Limits: If delays push construction beyond 18 months, you may incur extension fees or face full secondary underwriting.
Frequently Asked Questions About Construction Home Loans
Can I use land I already own as a down payment for my loan?
Yes. If you already hold title to the lot where you plan to build, your equity in the land can be credited directly toward your down payment requirements.
For instance, if your lot appraises at $60,000 and you owe nothing on it, that entire $60,000 serves as buyer equity. On a total combined project cost of $300,000, your land equity represents a 20% down payment, satisfying standard conventional down payment criteria without requiring out-of-pocket cash at closing.
What happens if construction takes longer than the allowed time limit?
Single-closing construction-to-permanent loans cap the maximum building phase duration at 18 months. If severe weather or labor shortages cause your build to exceed this window, your lender may require a formal loan extension or re-underwriting.
In scenarios where timeline caps are exceeded, credit documents must be updated, and a new property value review may be ordered. Maintaining open communication with your builder and loan officer helps track construction milestones to stay within permitted timelines.
Are mortgage payments required while my home is actively being built?
During active construction, you typically make interest-only payments based solely on the funds disbursed to the builder, rather than the full loan amount.
For example, if your total build loan is $400,000 but the builder has only drawn $100,000 for initial foundation and framing work, your monthly interest payment is calculated strictly on that $100,000 balance. Under certain government-backed options, like the FHA One-Time Close program, standard interim monthly payments can be structured so no payments are due from the borrower during the build phase.
Conclusion
Converting a construction loan into mortgage status does not have to be complicated. By selecting a single-close construction-to-permanent loan, you secure build funds and long-term 30-year financing in one streamlined transaction. This single-closing approach protects you against rising interest rates, avoids double closing costs, and removes the stress of re-qualifying after your home is complete.
At Capital Home Mortgage, as a direct lender offering complete custom build and government-backed loan solutions, our in-house underwriting teams guide you through builder reviews, draw management, and final loan conversion. If you are preparing to build in the Lone Star State, explore our dedicated resource on Texas construction home loans or contact our loan specialists today to start planning your build.


